This is the one week the entire Prosper roster is in the same room. Three days at The Wynn Las Vegas Resort – nine coaches, headline guests, live trading, and a floor full of traders leveling up together.
WE STAND CORRECTED
It was a brutal week for tech investors, and a volatile one for broader indexes, as midterm elections became a factor in an AI-related seesaw selloff. Worries of a potential slowdown in data center construction following big Democratic wins in the House and Senate and key state governorships hit U.S. markets hard on Thursday.
The heavy selling on Thursday sent the three major stock averages to their worst one-day losses since April 2025. The Nasdaq Composite tumbled 5.5%, closing more than 10% below its most recent high and putting it in what Wall Street regards as a correction. The broad-market S&P 500 lost 4.4%, while the Dow fell more than 1,800 points, or 3.4%. Tech stocks did bounce back on Friday but the Nasdaq Composite posted a fourth consecutive weekly decline.
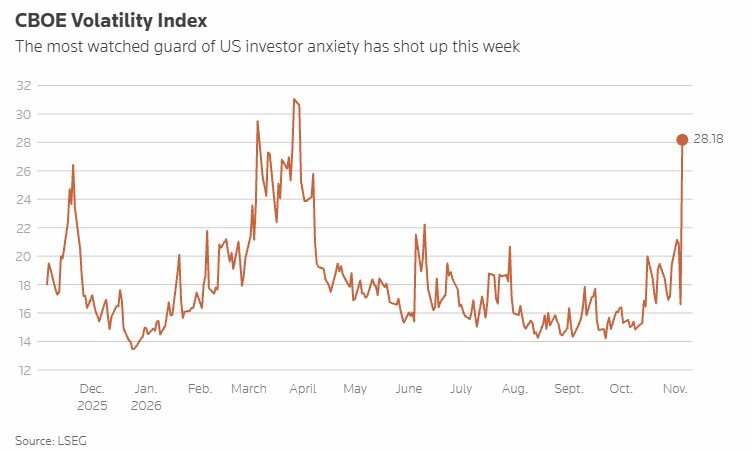
The CBOE Market Volatility Index (VIX) spiked for the week, and closed Friday at a still-elevated level near 25.64. With shorter-dated protection priced above longer-dated volatility, (Backwardation), VIX contracts suggest investors may be paying a premium to hedge near-term risk despite Friday’s rebound (more on that below).
On Friday, the Bureau of Labor Statistics reported that the U.S. economy added 165,000 jobs in October, well above consensus expectations. Payroll estimates for August and September were revised higher by a combined 84,000 jobs.
This week we will get the October CPI report as investors are expecting the Fed to raise rates in December to fight inflation. The US central bank held steady last month after hiking in September for the first time in three years.
For the week, the DOW lost -0.9 % to 51,286, the S&P 500 fell -2.7% to 7,377, the Nasdaq slumped -3.4% to 24,579 and the Russell 2000 lost -2.1% to 2,754. The CBOE VIX gained +32% to 25.64.
Correction Territory
A stock market correction is generally defined as a negative movement in major stock indexes — particularly the Dow Jones Industrial Average, S&P 500, or Nasdaq Composite — of 10% or more from recent highs. Generally speaking, corrections occur during bull markets, or uptrends in the stock market.
The Nasdaq Composite plunged into correction territory on Thursday. History shows more selling can follow in the near term, but a recovery eventually takes hold three months later.
The tech-heavy index slid more than 5% on Thursday, closing more than 11% below its record reached last month. On Wall Street, any decline greater than 10% is a correction. A 20% pullback qualifies as a bear market. Chip stocks tumbled Thursday, with the iShares Semiconductor ETF (SOXX) falling 12% and for its worst day since the Covid-19 breakout of March 2020.
Across 10 previous correction episodes over the last decade, selloffs in 2025, 2022, 2020 and 2018 were followed by further rough selling over the next one month. But the Nasdaq was back to rally mode again after six months for all those occasions except one: 2022.
Overall, the Nasdaq gained an average of 9.41% from the correction bottom over the following three months and 17.03% over six months.
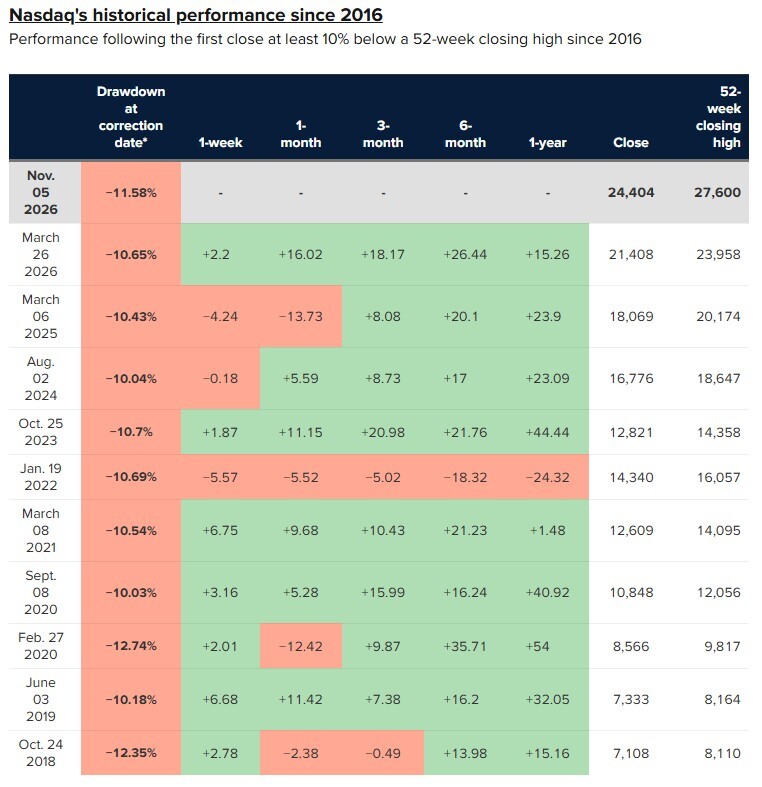
The January 2022 correction was the one that offered a harsher outcome. The Nasdaq lost another 18.3% over the next six months and was down 24.3% a year later. The catalyst for this correction was Democrats sweeping the House and Senate in Tuesday’s midterm elections. The party also made significant gains in Texas, where Gina Hinojosa won the race for governor after campaigning on an immediate moratorium for data center development.
Investors are now weighing whether tighter state-level restrictions could slow data center construction, putting pressure on companies tied to the artificial intelligence trade.
Frank Cappelleri, founder of CappThesis, pointed to past midterm election cycles for guidance and found that points to more volatility in the near term as well. The chart analyst said the Nasdaq was higher 12 months after the election in all but one of 13 midterm cycles since 1974.
Cappelleri pointed to 2018, when the Nasdaq rallied the day after Democrats won the House. A sharp December sell-off followed, but the index was ultimately about 15% higher a year after the election, he said.
VOLATILITY SPIKES AFTER MIDTERM RESULTS
U.S. equity markets experienced significant volatility following Election Day, as a Wednesday rally gave way to a sharp, broad-based sell-off on Thursday and then a partial recovery on Friday. Democrats’ stronger-than-expected electoral performance initially fueled optimism that a shift in the political landscape could ease geopolitical tensions, particularly with Iran.
Sharp gains on Wednesday in major equity indexes were accompanied by a slide in oil prices. That gave way on Thursday to steep equity declines, when the Cboe Volatility Index also hit a seven-month high.
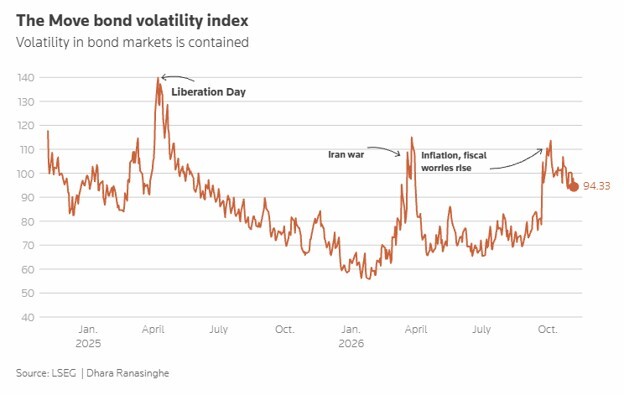
Unlike in the equity markets, bond markets are so far showing no signs of the sort of stress they came under during the COVID-19 pandemic or around the Liberation Day tariffs.
US 10-year Treasury yields have fallen 50 bps from peaks above 5% hit last month on concerns about high debt, rising inflation and competition for capital
as tech firms ramped up bond sales .
The closely watched MOVE index, which tracks volatility in the US Treasury market, hit a six-month high in October but has since slipped back,
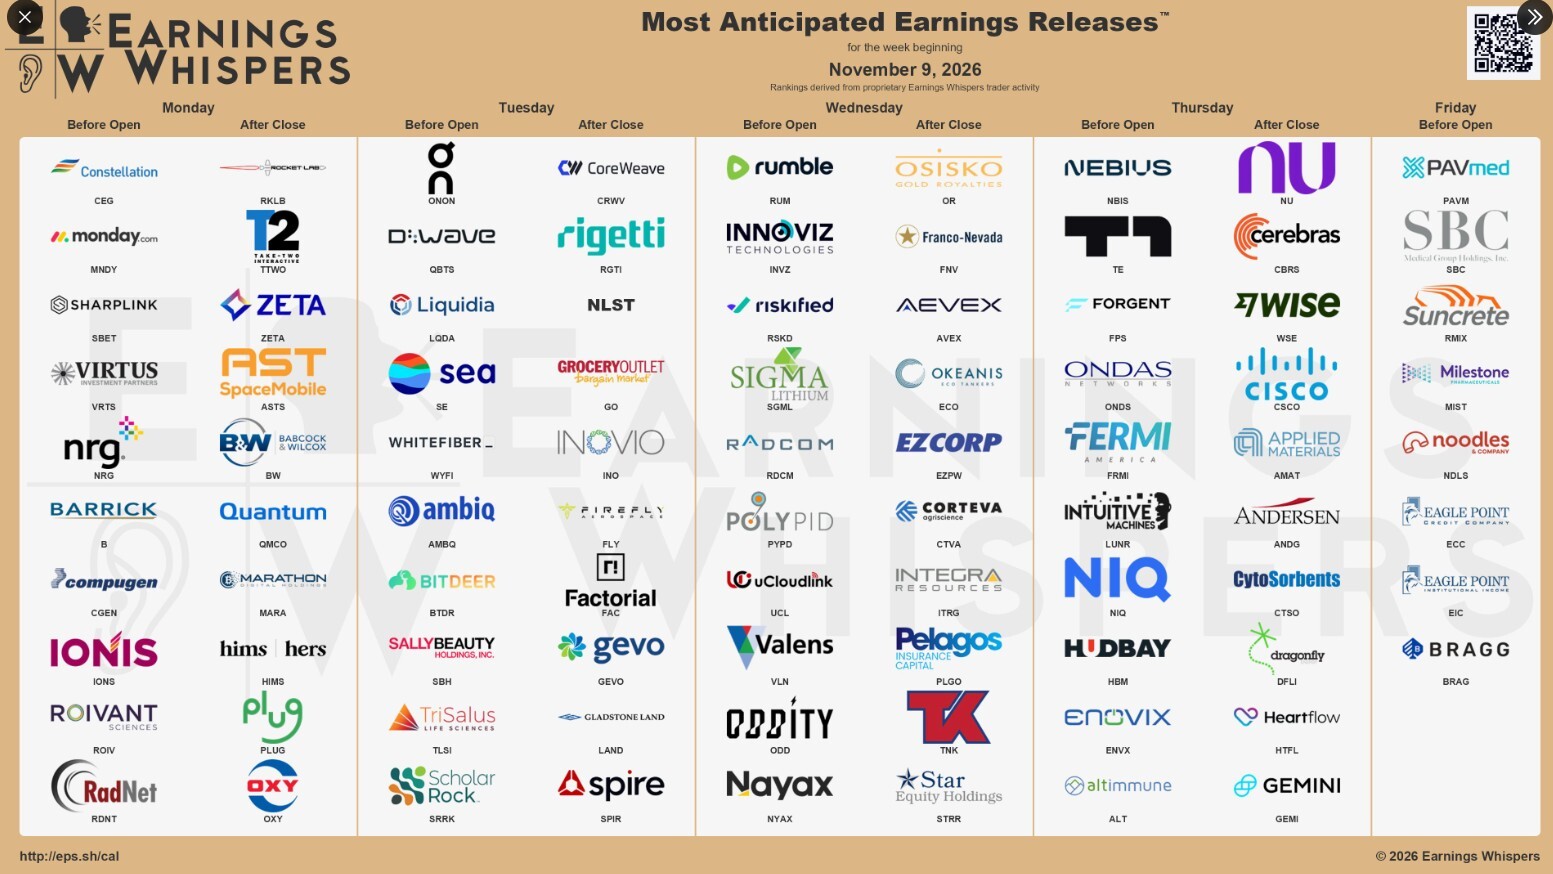
Economic Reports of Note (All Times EST):
Monday
10:00 am – US: Wholesale Inventories
10:00 am – US: Fed Member Goolsbee Speaks
10:30 am – US: Atlanta Fed GDPNow
11:00 am – US: NY Fed 1-year Consumer Inflation Expectations
11:00 am – US: 3 & 6–month Bill Auctions
12:15 pm – US: FOMC Member Barkin Speaks
1:00 pm – US: 3-year Note Auction
10:35 pm – JAP: 30-year JGB Auction
Tuesday
6:00 am – US: NFIB Small Business Optimism
8:15 am – US: ADP Employment Change
8:30 am – US: CPI
8:55 am – US: Redbook
10:00 am – US: Cleveland CPI
1:00 pm – US: 10-year Note Auction
Wednesday
5:00 am – US: OPEC Monthly Report
7:00 am – US: Mortgage Data
Thursday
2:00 am – UK: GDP
8:30 am – US: Weekly Jobless Claims
10:00 am – US: Existing Home Sales
11:30 am – US: 4 & 8-week Bill Auctions
12:00 pm – US: Crude Oil Inventories
1:00 pm – US: 30-year Bond Auction
Friday
5:00 am – EU: GDP
8:30 am – US: PPI